
Planning an exit in Indonesia starts with accepting that the market is big, active, and idiosyncratic. Indonesia is the largest economy in Southeast Asia and the 16th largest in the world, with GDP exceeding US$1 trillion in 2024 (Global Legal Insights, as cited by Lyndon Advisory). In M&A, Indonesia recorded 150 deals valued at US$14.2 billion in 2023 (White & Case and Mergermarket, as cited by Lyndon Advisory). That backdrop matters for founders and investors because it implies many potential counterparties, but also wide variation in deal readiness. ARMA Law notes that a business can look profitable on paper yet still be hard to sell once buyers test structure, governance, regulatory position, key contracts, ownership, and management continuity.
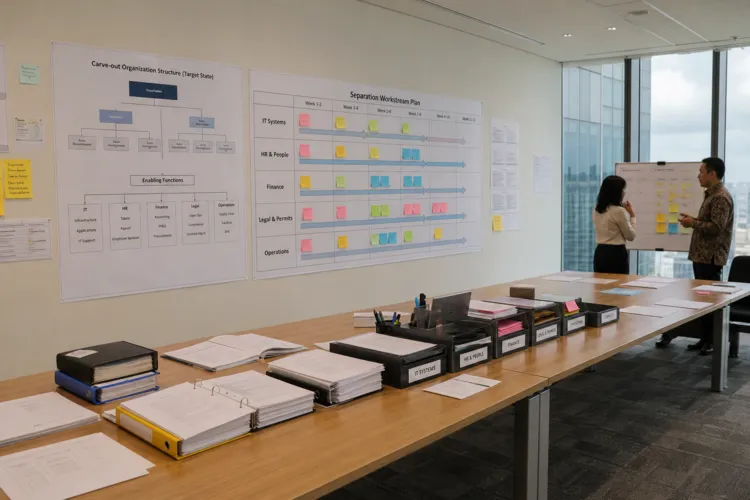
Divestment routes in Indonesian M&A usually begin with the most straightforward path: a sale of shares to another shareholder or a third-party buyer (ARMA Law). In practice, the route you choose gets constrained by how your company is documented and how cleanly it can pass a change-of-control review. Lyndon Advisory stresses that sellers who clean up related-party transactions, licences, land rights, and normalized EBITDA before buyer contact can create competitive tension, while waiting until after the first approach can hand control of disclosure, timing, and price to the buyer. This is where exit planning stops being theoretical and becomes operational: you are preparing for a buyer’s diligence process, not just negotiating a headline valuation.
Buyer Pools in Indonesia: Domestic Conglomerates, PE, and Special-Case Domestic Buyers
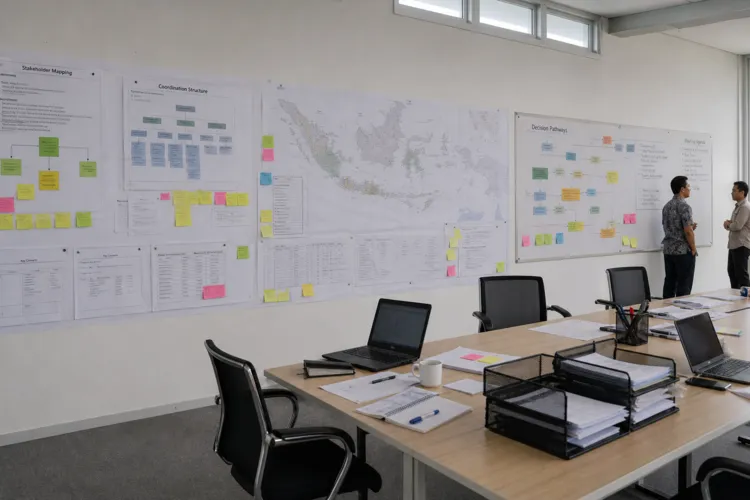
Buyer mapping should separate strategic domestic acquirers, regional strategics, and financial sponsors, because they value risk differently. Lyndon Advisory describes Indonesia’s M&A market as dominated by domestic conglomerates and state-owned enterprises, with regional strategic buyers active and financial sponsors playing an increasingly important but still secondary role. Private equity buyers can pay for quality and use more sophisticated valuation methods, but they demand clean financials and a structured diligence process (Lyndon Advisory). Lyndon also notes that PE-backed exits typically achieve higher multiples than first-time founder exits because the business is already presented with institutional governance and financial reporting.
Some exits depend on who can legally hold the asset at all, which narrows the buyer pool and changes pricing power. Victaura highlights that in Bali and Lombok only Indonesian citizens can hold Hak Milik, under Article 21 of Law 5 of 1960, making the domestic buyer the counterparty who can take top title. Remaining tenure can become a pricing input when the right being transferred is time-bound. Under Government Regulation 18 of 2021, Article 37, a building right held through a foreign-owned company runs up to 30 years, extendable by 20 and renewable by 30 on state or Hak Pengelolaan land, and up to 30 years renewable by deed on Hak Milik land. In parallel, Victaura notes Bali recorded 6,948,754 direct foreign arrivals in 2025, up 9.72%, with Australia at 1.63 million (BPS Bali), but arrivals measure visitors, not buyers.
Valuation reality is shaped by both macro conditions and the buyer’s confidence in cash conversion. Victaura reports Bank Indonesia’s national Residential Property Price Index at 110.60 in Q1 2026, up 0.62% year on year, while primary sales fell 25.67% (Bank Indonesia Residential Property Survey Q1 2026). As of the 23 September 2026 decision, the BI Rate was held at 5.75% (reported by Antara). These are national indicators, not deal-by-deal pricing rules, but they frame underwriting assumptions and financing appetite. On tax and proceeds, Lyndon Advisory states that for most mid-market founders selling at meaningful valuations, the applicable marginal rate will be the 35% bracket, while non-resident sellers face a standard statutory withholding tax rate of 20% on gross proceeds under Article 26 of the Indonesian Income Tax Law (treaties may modify outcomes for some jurisdictions).
What are common divestment routes for an exit in Indonesia?
Who are the main buyer pools in Indonesia M&A?
How do land rights affect exit options in Bali and Lombok?
What indicators can shape valuation expectations during an Indonesia exit?
What should an exit strategy for Indonesia investment prioritize before contacting buyers?