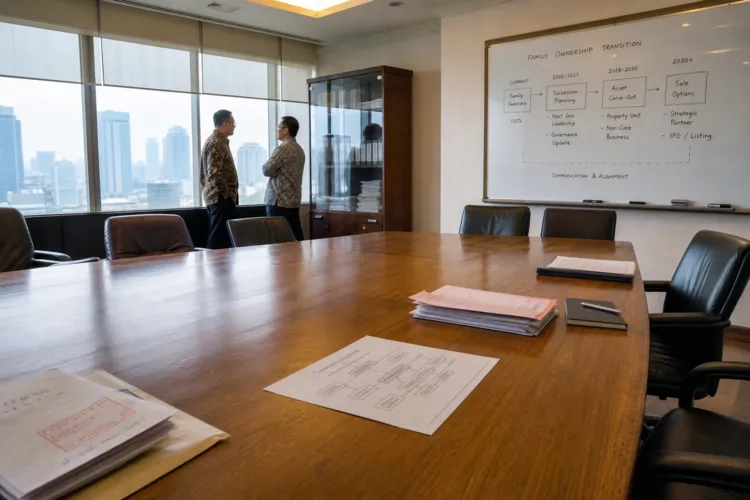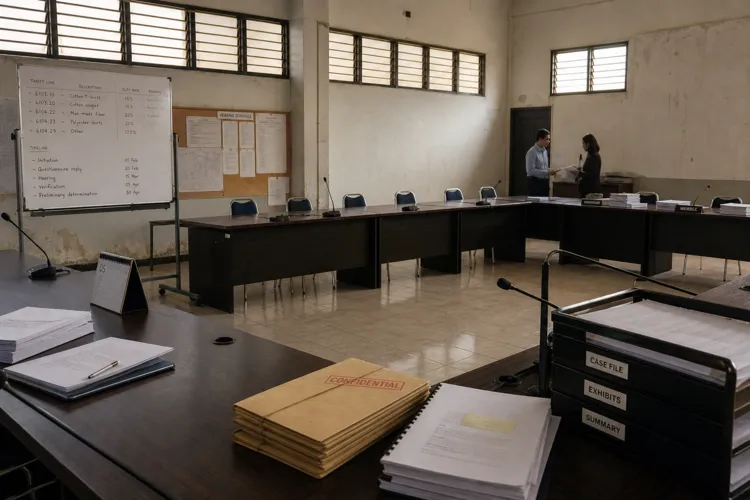
Distressed deals in Indonesia can look like straightforward bargain hunting, but the core issue is legal pathway risk. A buyer is not only choosing an asset and a price; the buyer is also choosing a court-supervised process that can determine what can actually be transferred and by whom. Practitioner guidance on distressed M&A stresses a simple but unforgiving question: are you buying an asset, a business, or a liability trap? That question becomes decisive when the target is already inside PKPU (a suspension of debt payment obligations) or has moved into formal bankruptcy, because control, approvals, and timing differ from standard M&A.
Indonesia’s formal distress mechanisms sit under Law No. 37 of 2004 and are administered through the Commercial Court (Pengadilan Niaga). PKPU is described as a court-supervised debt restructuring process that gives the debtor time to negotiate and agree on a composition plan (rencana perdamaian) with creditors while enforcement actions are stayed. Bankruptcy (kepailitan), in contrast, is a liquidation process where assets are distributed to creditors through a court-appointed receiver or trustee (kurator). Commentary also notes measurable distressed-market activity since 2022 and a growing docket of PKPU filings at the Commercial Court in Jakarta, with infrastructure, property, and telecoms described as sectors most affected by post-pandemic capital stress and rising financing costs.
PKPU vs Bankruptcy: Where Acquisition Leverage Really Sits
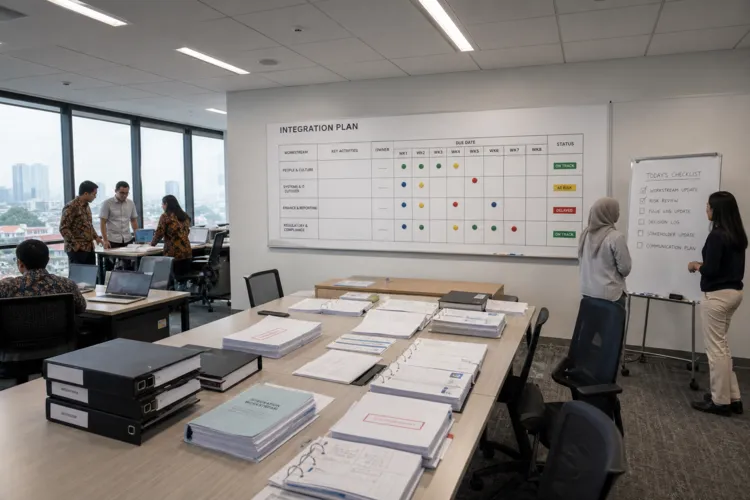
For distressed asset acquisition in Indonesia, the PKPU-bankruptcy distinction determines who you negotiate with and how much leverage you can realistically obtain. In PKPU, the distressed firm’s management negotiates under court supervision, and major asset transactions usually need administrator (pengurus) oversight. In bankruptcy, the kurator manages and sells the estate under the supervision of a supervisory judge (hakim pengawas), with a mandate to maximize returns for unsecured and undersecured creditors. Practical restructuring guidance adds that approval of a PKPU plan requires agreement from at least 50% of secured and unsecured creditors representing two-thirds of total claims, and if the plan is rejected or the company fails to perform, the court can declare bankruptcy.
Bankruptcy sale routes can also create distinct entry points. A bankruptcy asset sale process begins once the Commercial Court declares a debtor bankrupt, or when assets are liquidated during or after a failed PKPU restructuring. Investors are described as finding opportunities via court-supervised auctions and trustee-led disposals, including purchases of plant, land, receivables, and going concerns at discounts, but with strict procedures. Buyers should expect KYC and anti-money-laundering checks and a requirement to show credible proof of funds before a bid is accepted. Foreign bidders are generally permitted to participate, but the guide flags that sectoral rules under the Positive Investment List and the risk-based licensing regime administered through the Ministry of Investment/BKPM and the OSS system may cap or condition foreign ownership in certain activities.
Execution discipline matters because distress is not automatically value. A comparative investor note from India’s IBC context emphasizes that the key question is not whether a distressed asset is available cheaply, but whether it can create value after acquisition. That logic translates cleanly to Indonesian PKPU and bankruptcy situations: a low price cannot fix obsolete technology, a disappeared market, or a non-viable model. Deal teams should focus on root-cause analysis of the failure, then map it to the process constraints: whether the seller actually has authority to transfer the asset, what court or administrator approvals are needed, and whether the post-close plan depends on licenses or ownership structures that must align with Indonesia’s investment framework.
How do PKPU and bankruptcy create acquisition opportunities in Indonesia?
Who do buyers negotiate with in PKPU versus bankruptcy?
What creditor approval threshold applies to a PKPU composition plan?
What should foreign investors check before bidding on bankruptcy assets?
What is the biggest risk in distressed asset acquisition in Indonesia?