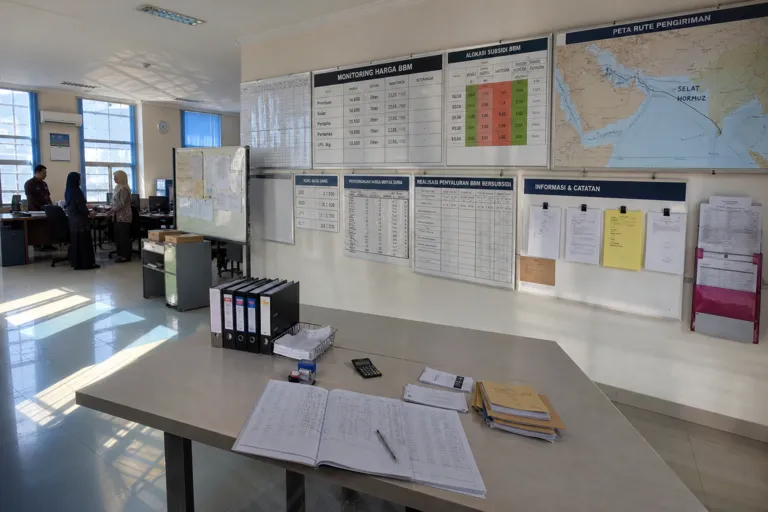
The Strait of Hormuz disruption that followed the US and Israel offensive against Iran on 28 February 2026 quickly became a global energy shock with local consequences for Indonesia. An ORF paper describes Hormuz as a chokepoint through which roughly 20% of global petroleum supply and up to 30% of global LNG normally flows, while the IEA labelled the disruption “the largest supply shock in the history of the global oil market.” By early July 2026, traffic was about 27 transits per day versus a pre-war baseline of 84, and war-risk insurance premiums remained at eight times pre-crisis levels. For Indonesia, this translated into a harsher import bill and a more fragile operating environment for keeping domestic prices stable.
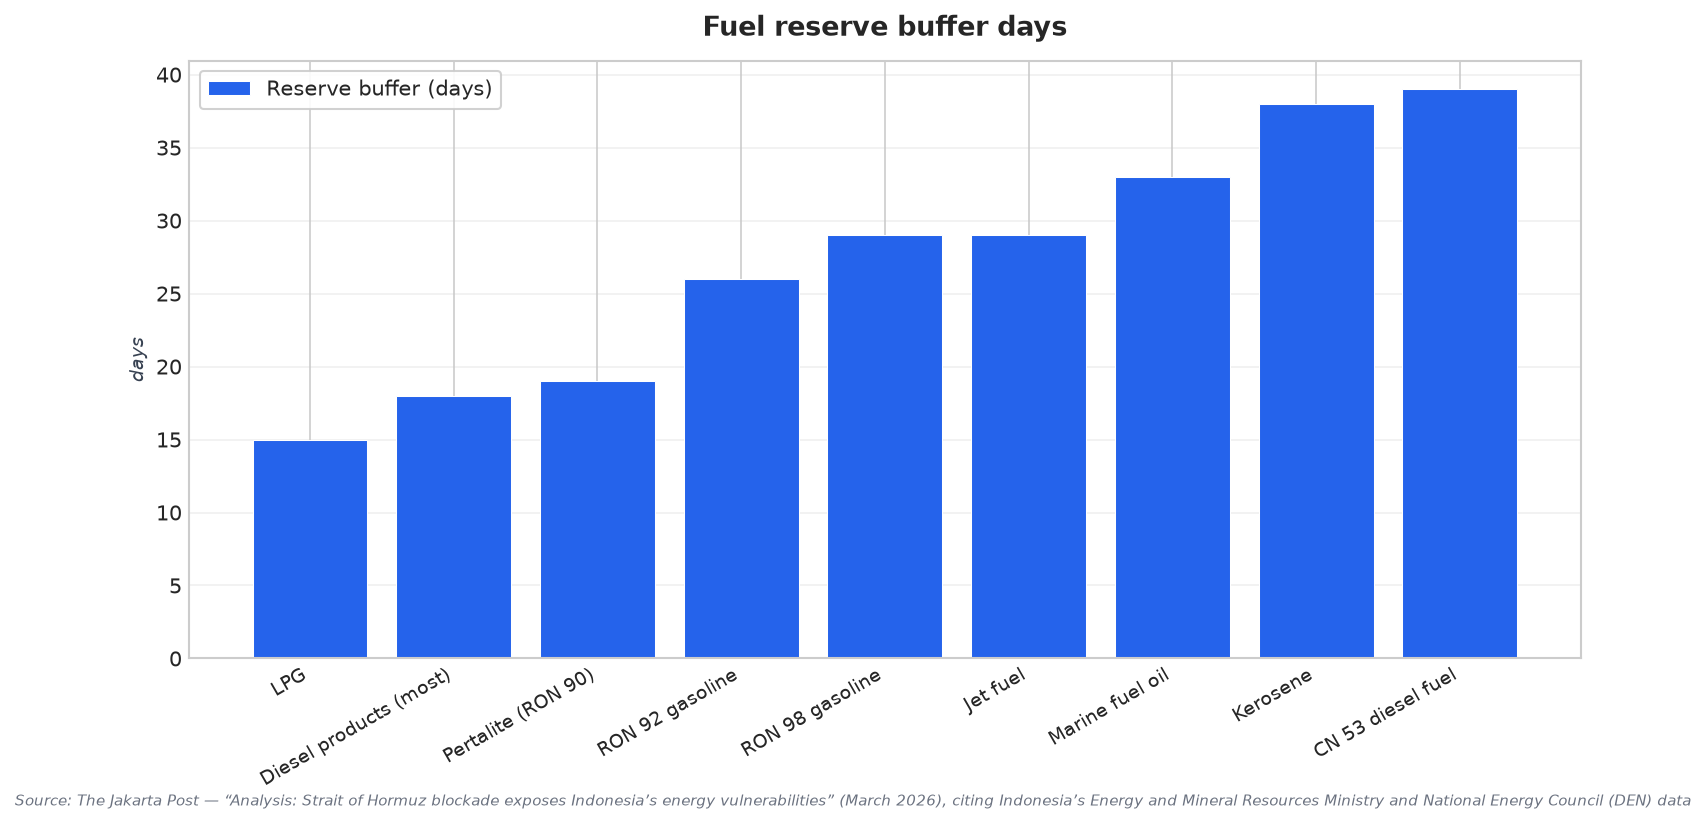
Energy security is the first pressure point. A Jakarta Post analysis said around 25% of Indonesia’s oil imports originate from the Middle East and pass through the strait, while domestic fuel reserves can only last for around 20 days. Official data cited there put 2024 domestic fuel consumption at 82.9 million kiloliters, or about 227,136 kL per day, and the Energy and Mineral Resources Ministry estimated stockpiles provide only 20–25 days of buffer. Product-specific buffers are thinner: LPG at 15 days, most diesel products around 18 days, and subsidized Pertalite (RON 90) at 19 days, with RON 92 at 26 days and jet fuel around 29 days. These figures leave Indonesia exposed when shipments tighten and prices spike.
Subsidies Meet the Rupiah: A Two-Sided Shock
The economic strain is intensified by how subsidies and the exchange rate interact. The 2026 APBN assumed an Indonesian Crude Price of USD 82 a barrel and a rupiah of IDR 15,300 per US dollar, but those assumptions were overtaken by market moves as the Hormuz crisis spread through pricing and risk channels. Bank Indonesia raised its benchmark 7-day reverse repo rate to 5.25% on May 21, 2026, as the rupiah hit a record low of IDR 17,600 per US dollar; the same source said the currency had depreciated 5% year-to-date. Middle East Monitor also warned that a weakening rupiah compounds subsidy costs by raising the local-currency price of imported fuel and increasing subsidy obligations, narrowing fiscal space just as policymakers try to keep inflation contained.
Indonesia’s near-term response has combined price freezes for subsidized fuels with higher market prices for non-subsidized grades. The Southeast Asia Desk reported subsidized Pertalite and Biosolar were kept unchanged at Rp10,000 and Rp6,800 per liter, respectively. At the same time, Indoneo reported Pertamina raised Pertamax (RON 92) to IDR 16,250 per litre in Jakarta on June 10, 2026, up from IDR 12,300, and Pertamax Green 95 to IDR 17,300 per litre from IDR 13,900, citing higher global oil prices and a weaker rupiah. This approach aims to concentrate relief, but it also highlights how quickly the subsidy “math” can diverge from budget assumptions when oil and FX move together.
The wider risk is that the shock becomes both an inflation and fiscal credibility problem at once. Middle East Monitor described a convergence of energy inflation and food inflation risks, pointing to drought concerns linked to a potential super El Niño and rising fertilizer and logistics costs tied to petrochemical supply disruption. ORF added that higher energy prices feed into food inflation, noting food accounts for 25–35% of ASEAN CPI baskets, a structure that can compress purchasing power and put central banks in a stagflationary bind. Meanwhile, Savage Minds noted Bank Indonesia interventions in spot and forward markets using roughly USD 136 billion of foreign reserves, and flagged that the fiscal deficit hovers near the legally mandated ceiling of 3% of GDP. In this Strait of Hormuz impact Indonesia moment, the hard choice is how to preserve household support without exhausting fiscal room.
How is the Strait of Hormuz impacting Indonesia’s economy right now?
How much of Indonesia’s oil imports are linked to the Middle East and Hormuz routes?
How long can Indonesia’s fuel reserves last during supply stress?
What assumptions did Indonesia’s 2026 budget use for oil and the rupiah?
Which fuel prices were kept fixed, and which were raised?